
Best Canadian Bank for Small Business
Find out which Canadian bank offers the best accounts, lending products, and services for small business owners and startups.
Choosing the right bank matters. Clear guidance for small businesses: discover which Canadian bank offers the best accounts, fees, and services for your needs.
Ratesopedia’s Take: No single Canadian bank dominates for all small businesses. RBC and TD lead for digital features and branch access, while credit unions like Innovation Federal offer lower fees. Newer platforms such as Venn and Wise excel at multi-currency needs. Your best choice depends on transaction volume, international payments, and whether you prioritize branch access or digital efficiency.
What Small Businesses Need From a Bank
Small business banking differs fundamentally from personal accounts. You face higher transaction volumes, tax obligations, payroll requirements, and potentially international payments. The right bank should reduce overhead costs while supporting growth.
Four factors drive most decisions: monthly fees and transaction limits, digital platform quality, lending access, and multi-currency capabilities. If your business handles cash deposits, branch network matters. If you invoice US clients, foreign exchange rates become critical.
- Transaction volume: Calculate your monthly debits, credits, and e-Transfers to avoid overage charges.
- Digital integration: QuickBooks or Xero compatibility saves hours during tax season.
- Lending relationships: Established bank connections ease future loan applications.
- Currency needs: USD accounts reduce foreign exchange markups if you work across borders.
Consider starting with your current transaction patterns. Track one month of business activity to identify actual needs before committing to an account.
Big Six Banks: Traditional Strength
Canada’s major banks—RBC, TD, BMO, CIBC, Scotiabank, and National Bank—control most small business lending. They offer stability, extensive branch networks, and established credit products. Rates and terms may vary by financial institution.
| Bank | Entry Account | Monthly Fee | Transactions | Best For |
|---|---|---|---|---|
| RBC | Digital Choice Business | $6 | Unlimited digital | Digital-first operations |
| TD | Basic Business Plan | $5 | 5 included | Low-volume startups |
| BMO | Business Start | $6 | 7 included | New entrepreneurs |
| CIBC | Everyday Business | $20-$25 | 30 included | Growing businesses |
| Scotiabank | Select Account Plan A | $20 | 25 included | Balanced needs |
| National Bank | Hybrid Package | $8 | 6 included | Quebec-based firms |
RBC Digital Choice Business Account
At $6 monthly, this account provides unlimited electronic transactions, 10 free Interac e-Transfers, and strong mobile banking. RBC’s platform integrates well with accounting software and supports both CAD and USD accounts.
- Digital efficiency: Unlimited online debits and credits suit high-volume digital businesses.
- Branch network: Canada’s largest branch system supports occasional cash needs.
- Lending access: Existing relationships simplify future credit applications.
- In-branch fees: Physical transactions cost extra beyond the digital limit.
- FX markups: Foreign exchange spreads reach 2-3% versus specialized platforms.
TD and BMO Entry Options
TD’s Basic Business Plan starts at $5 with 5 monthly transactions, charging $1.25 per additional transaction. BMO’s Business Start Plan offers 7 transactions for $6. Both suit side businesses or seasonal operations with minimal activity.
If you process 20-30 transactions monthly, mid-tier plans become cost-effective. TD’s Everyday Business Plan B ($39) includes 60 transactions with fee waivers on a minimum balance. BMO’s Enhanced Business Account ($50, waived with $35,000 balance) provides 70 transactions and $4,000 cash deposit capacity.
If you also need a card for operating expenses, compare its fees separately from the chequing account fees. The BMO CashBack World Elite Business Mastercard may suit businesses that regularly charge fuel or shipping and pay their balances in full. See how BMO’s business cash back stacks up after fees for four sample budgets.
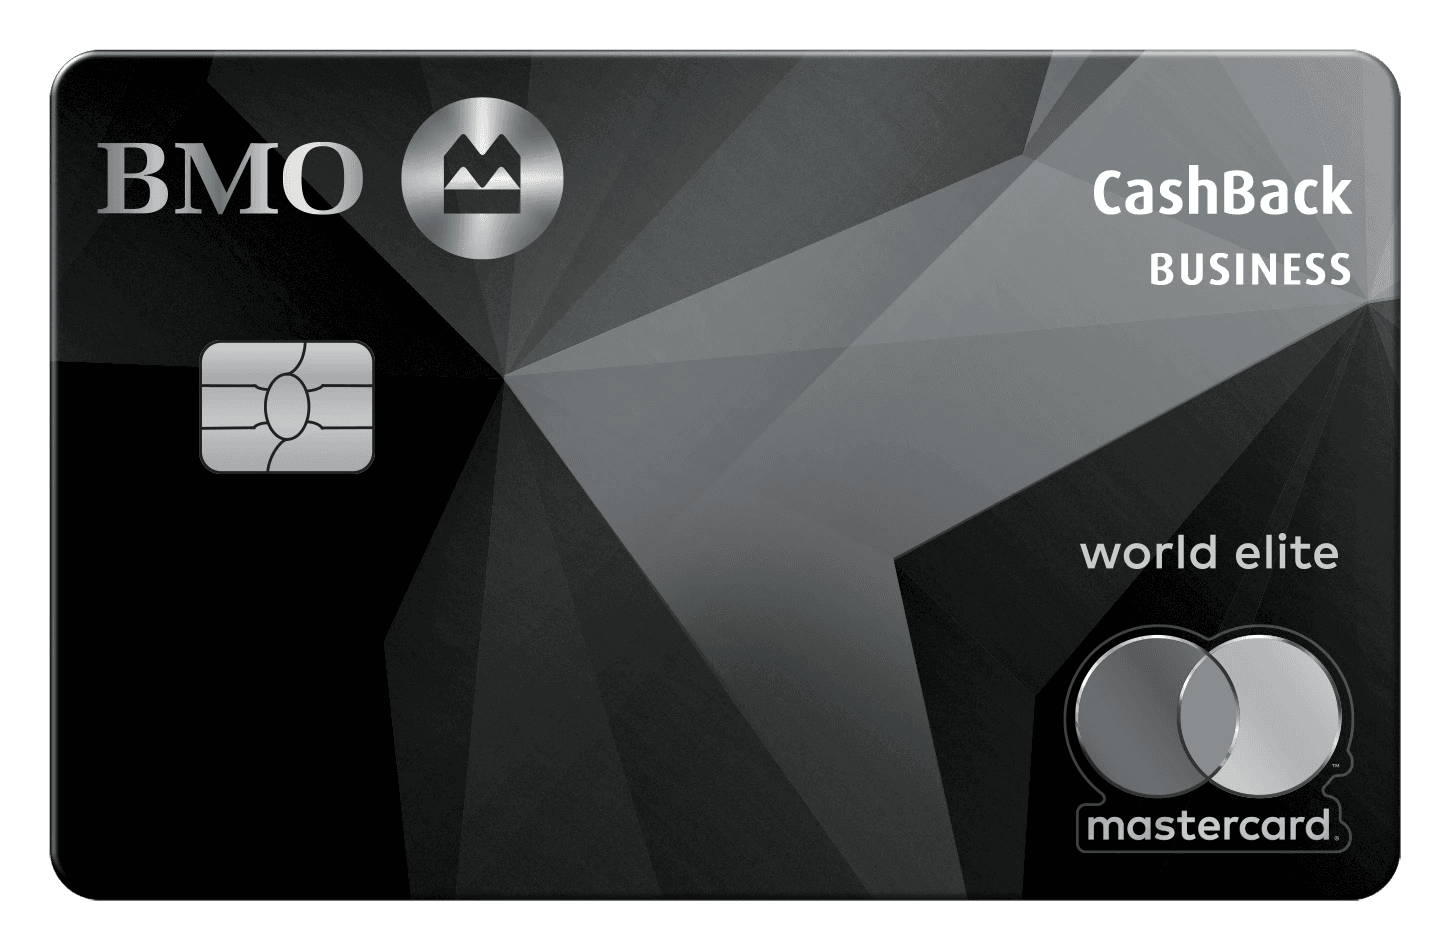
- Annual feeNo annual fee the first year
- $0 $175
- First year free
- Our valuationMilesopedia first-year estimate First-year valueConditional welcome cash backUp to $900Annual fee rebated$175TotalUp to $1,075Up to 15% cash back in the first three billing cycles, up to $900, on up to $6,000 in purchases allocated according to BMO’s category limits.
- Up to $1,075
- Welcome offer
- Up to 15% cash back in the first three billing cycles, up to $900, on up to $6,000 in purchases allocated according to BMO’s category limits.
- Ends Dec 14, 2027
on BMO's website
High-Volume Unlimited Plans
Businesses exceeding 100 monthly transactions should evaluate unlimited plans. CIBC’s Unlimited Business Operating Account ($65, waived with $45,000 balance) removes transaction anxiety and includes free international money transfers through CIBC Global Money Transfer.
Scotiabank’s Unlimited Plan ($120, waived with $75,000) permits unlimited deposits and up to $30,000 monthly cash deposits. TD’s Unlimited Business Plan ($125, waived with $65,000) adds unlimited Interac e-Transfers and merchant service fee rebates.
Digital Banking Platforms
Newer platforms challenge traditional banks on fees and international capabilities. Venn, Wise, and Airwallex target businesses frustrated by legacy banking limitations, particularly around foreign exchange and digital integrations.
Venn: Multi-Currency Leader
Venn provides local CAD, USD, EUR, and GBP accounts without monthly fees on its Essentials plan. The platform’s USD account handles ACH transfers directly, eliminating the SWIFT wire fees that plague Canadian businesses receiving US payments.
Foreign exchange spreads range from 0.25% to 0.45% depending on plan tier—substantially below the 2-3% typical at major banks. For a business converting $10,000 USD monthly, this difference represents $1,000-$2,500 annual savings. Rates and terms may vary by financial institution.
- 1% unlimited cashback: Corporate cards return cash on all purchases without category restrictions.
- Accounting integration: Direct QuickBooks and Xero connections automate reconciliation.
- No minimum balance: Start with any amount, unlike traditional banks requiring thousands.
- 2% interest: CAD and USD balances earn interest regardless of amount.
- No cash deposits: Retail businesses need a traditional bank for physical currency handling.
- No branch network: All support occurs digitally through chat and email.
Wise Business: Global Transfers
Wise specializes in transparent international payments using mid-market exchange rates. The platform holds balances in 40+ currencies and provides local bank details for major markets, allowing businesses to receive payments as domestic transactions.
No monthly fee applies, with costs charged per transaction. Batch payment capabilities suit businesses managing international payroll or multiple suppliers. Integration with Xero and QuickBooks streamlines bookkeeping for cross-border operations.
Credit Unions: Lower Fees
Credit unions operate as member-owned co-operatives, often delivering better rates and lower fees than major banks. Regional focus means services vary by province, but competitive offerings exist nationwide.
Innovation Federal Credit Union
This Saskatchewan-based institution offers remarkably competitive business accounts. The no-fee USD Business Account provides unlimited transactions at $0 monthly cost—unmatched by any major bank for US dollar operations.
The Business Account Package 2 ($20 monthly, waived with minimum balance) includes 50 transactions. Package 6 ($110, waived with balance) provides unlimited daily banking for high-volume businesses at costs below Big Six equivalents.
Coast Capital Savings
British Columbia’s Coast Capital targets community groups and small businesses with specialized accounts. The Community Chequing account offers unlimited transactions at $0 monthly fee for registered non-profits and charities.
Business Premium Chequing ($65, waived with minimum balance) competes directly with Big Six unlimited plans while including priority support and partner rebates. A welcome bonus of up to $450 may be available for new accounts.
| Credit Union | Account | Fee | Transactions | Geographic Note |
|---|---|---|---|---|
| Innovation FCU | USD Business | $0 | Unlimited | Not available Quebec |
| Innovation FCU | Package 2 | $20 | 50 | Saskatchewan-based |
| Coast Capital | Community Chequing | $0 | Unlimited | Non-profits only |
| Coast Capital | Premium Chequing | $65 | Unlimited | BC-based, national access |
| Alterna Bank | eChequing | $0 | Unlimited digital | $3,000 minimum balance |
Lending and Credit Products
Banking relationships often determine lending access when your business needs capital. Most Canadian small business loans flow through the Big Six banks, making account choice strategically important beyond daily banking.
Canada Small Business Financing Program
The CSBFP provides government-backed loans through virtually all major banks and many credit unions. The program covers up to 85% of lender losses, encouraging approval of applications that might otherwise be declined.
- Term loans: Up to $1 million for equipment, land, buildings, or leasehold improvements.
- Lines of credit: Up to $150,000 for working capital needs.
- Interest rates: Variable at prime plus 3%, or fixed at residential mortgage rate plus 3%.
- Fees: 2% registration fee and 1.25% annual administration fee apply.
- Eligibility: Annual gross revenues must stay under $10 million.
Establishing a business account with a participating bank positions you for easier CSBFP access. Most lenders prefer existing customers with demonstrated transaction history when evaluating applications.
Business Development Bank of Canada
BDC focuses exclusively on business lending with more flexible criteria than commercial banks. If traditional banks decline your application, BDC represents a strong alternative for businesses with solid plans but limited operating history.
BDC doesn’t offer business chequing accounts, so you’ll need a separate banking relationship. Many small businesses combine a Big Six account for daily banking with BDC for specialized financing needs.
Alternative Lenders
Online lenders like OnDeck Canada, Lending Loop, and FundThrough provide faster approval than traditional banks. Interest rates exceed bank rates substantially—often 20-40% APR—making them suitable only for urgent, short-term needs.
These lenders typically don’t require existing banking relationships, evaluating applications based on revenue and cash flow rather than bank history. Consider them supplementary rather than primary financial partners.
Matching Banks to Business Types
Your business model determines ideal banking features. An ecommerce operation needs different tools than a construction firm or consulting practice.
Ecommerce and Online Businesses
Digital businesses benefit most from platforms like Venn or Wise. If you receive Stripe or Shopify payouts in USD, a true US account eliminates the 1.5% cross-border fee charged when forcing payouts into Canadian accounts.
Accounting software integration becomes critical during tax season. Direct QuickBooks or Xero connections save hours of manual reconciliation. Among traditional banks, RBC offers the strongest digital integrations for business credit cards and accounts.
Retail and Restaurants
Cash-heavy businesses require branch access and merchant services. TD and BMO excel here with extensive branch networks and integrated point-of-sale solutions. Both offer Moneris integration—Canada’s largest payment processor.
Evaluate cash deposit limits carefully. Scotiabank’s unlimited plan allows $30,000 monthly cash deposits before surcharges apply, while CIBC’s unlimited account caps cash at $15,000 monthly. Coin deposits typically cost extra at all institutions.
Professional Services and Consulting
Service businesses with minimal cash handling should prioritize digital efficiency and international payment capabilities. If you invoice US clients regularly, platforms like Venn or Wise reduce foreign exchange costs dramatically.
RBC’s Digital Choice Business Account works well for consultants with moderate transaction volumes who occasionally need branch access. Pair it with Wise for international invoicing to get the best of both approaches.
Startups and Tech Companies
Early-stage companies benefit from no-fee options that scale as the business grows. Venn’s Essentials plan ($0) or Alterna Bank’s eChequing (free with $3,000 balance) minimize fixed costs during the critical early months.
As revenue grows, migrating to accounts with better lending relationships makes strategic sense. Establishing a track record with RBC or TD positions you for future credit lines or equipment financing when needed.
Making Your Decision
Start by calculating your actual monthly transaction count. Review three months of business activity to identify patterns. Count debits, credits, e-Transfers, cash deposits, and cheque deposits separately.
Compare total monthly costs across institutions based on your specific usage. A $5 account charging $1.25 per extra transaction becomes expensive quickly if you process 40 monthly transactions. The $39 mid-tier plan with 60 included transactions costs less in that scenario.
- Track usage first: One month of data reveals whether you need 10 or 100 monthly transactions.
- Calculate total cost: Add monthly fees plus expected overage charges for accurate comparison.
- Factor growth: Choose an account with room to scale rather than switching later.
- Test digital tools: Sign up for demos of accounting integrations before committing.
- Consider geography: Branch access matters differently depending on your location and industry.
If international payments represent more than 10% of revenue or expenses, prioritize platforms with transparent foreign exchange. The 2-3% markup at traditional banks compounds quickly on volume.
For detailed comparisons of account features and current promotional offers, explore our comprehensive guides to business credit cards and banking products across Canada.
Bottom Line
The best Canadian bank for your small business depends on transaction volume, international needs, and growth plans. RBC and TD deliver strong digital platforms with lending access. Credit unions like Innovation Federal and Coast Capital offer lower fees with regional focus. Digital platforms such as Venn and Wise excel at multi-currency operations and foreign exchange transparency.
Most businesses benefit from starting with accurate usage tracking before choosing. Calculate monthly transactions, estimate cash deposit needs, and evaluate international payment frequency. Many successful operations use hybrid approaches: traditional banks for cash and lending, digital platforms for international efficiency.
Stay informed about the latest banking developments and exclusive financial insights by signing up for our newsletter—we deliver actionable guidance directly to your inbox each week.
Which Canadian Bank Is Best for Small Business – FAQ
Which Canadian bank has the lowest fees for small business accounts?
Innovation Federal Credit Union offers a no-fee USD business account with unlimited transactions. Among major banks, TD’s Basic Business Plan starts at $5 monthly with 5 transactions, while RBC’s Digital Choice Business Account costs $6 with unlimited digital transactions. Alterna Bank’s eChequing is free with a $3,000 minimum balance.
Do I need a business account if I’m a sole proprietor?
Legally, sole proprietors can use personal accounts for business transactions in Canada. However, separating business and personal finances simplifies bookkeeping, tax filing, and expense tracking. Most accountants recommend dedicated business accounts once revenue exceeds $30,000 annually or transaction volume makes tracking difficult.
Which bank is best for small business loans in Canada?
Canada’s Big Six banks (RBC, TD, BMO, CIBC, Scotiabank, National Bank) all participate in the Canada Small Business Financing Program and offer the lowest interest rates. BDC provides more flexible criteria for businesses with shorter operating histories. Existing banking relationships typically improve loan approval odds and terms.
What’s the difference between business chequing accounts at big banks versus credit unions?
Big banks offer extensive branch networks, sophisticated digital platforms, and comprehensive lending products. Credit unions typically provide lower fees, personalized service, and competitive rates with regional focus. Technology and international capabilities generally favour major banks, while local lending decisions and fee structures often favour credit unions.
Should I use a digital platform like Venn or Wise instead of a traditional bank?
Digital platforms excel at multi-currency operations, foreign exchange transparency, and accounting integrations. They work best for businesses with international clients, online operations, or significant USD transactions. Traditional banks remain necessary for cash deposits, in-person services, and established lending relationships. Many businesses use both strategically.
How much does a small business bank account cost in Canada?
Monthly fees range from $0 to $125 depending on transaction limits. Entry-level accounts cost $5-$8 with 5-10 transactions included. Mid-tier plans run $20-$50 with 30-70 transactions. Unlimited plans cost $65-$125 but waive fees with minimum balance requirements of $35,000-$75,000. Rates and terms may vary by financial institution.
Which bank offers the best USD business account in Canada?
Innovation Federal Credit Union’s no-fee USD Business Account provides unlimited transactions at no monthly cost. Among digital platforms, Venn offers true US account capabilities with ACH transfers and competitive foreign exchange rates of 0.25-0.45%. Traditional banks charge monthly fees plus significant FX markups of 2-3% on conversions.
Can I open a business bank account online in Canada?
Yes, most Canadian banks and all digital platforms allow online business account opening. You’ll need business registration documents, identification, and business numbers. Digital platforms like Venn and Wise complete the process entirely online. Traditional banks may require branch visits for certain account types or incorporated businesses.